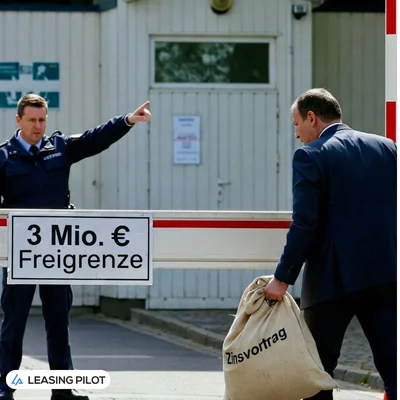
Caution at the Interest Barrier!
Please maintain a sufficient buffer below the threshold of EUR 3 million net interest expense!
👉 Because once an interest carryforward has been built up, it makes it harder to utilize the threshold in subsequent years!
The 3-month EURIBOR has risen significantly (most recently 2.676%; early 2026: 2.029%), which increases the interest expense on variable-rate financing.
This rise can create tax problems for highly leveraged companies such as LBOs or infrastructure & real estate AssetCos.
The majority of German companies are only unaffected by the interest barrier because they can rely on the exemption provided by the threshold.
As a reminder:
🔹 The interest barrier limits the tax deduction of interest expense to 30% of domestic tax EBITDA, and
🔹 the threshold stipulates that the interest barrier does not apply if net interest expense — i.e., interest income less "interest" expenses — is below EUR 3 million p.a.
What many underestimate:
Even reaching or slightly exceeding the threshold of EUR 3.0 million triggers the full effect of the interest barrier — with negative consequences for the current year and for subsequent years!
While the portion of interest expense that cannot be claimed is generally carried forward as an interest carryforward without time limitation,
this interest carryforward has negative consequences for subsequent years:
👉 The interest carryforward makes it more difficult (and potentially prevents) drawing the "interest barrier free pass" in the form of the threshold in future years, as the existing interest carryforward is included in the net interest expense of the following year.
👉 Even if the company remains below the threshold of EUR 3.0 million in the following year despite the inclusion of the interest carryforward, unrestricted deductibility applies only to the current interest expenses of that year; the accumulated interest carryforward itself remains difficult to utilize.
👉 It is therefore advisable to ensure that you always maintain a sufficient safety buffer below the threshold and avoid building up an interest carryforward!
Now the good news:
This is quite straightforward!
We can support you efficiently in reducing the relevant interest expense!
Let's talk!
#InterestBarrier #Treasury #CFO #LBO #PrivateEquity
Caution at the Interest Barrier!